Market Updates
2027 Conforming Loan Limits in Florida: Some Lenders Are Already Going Up to $850,000
FHFA has not announced the official 2027 conforming loan limit yet, but several lenders have already introduced early conventional limits between $845,000 and $850,000. See what's official, what's lender-specific, and what Florida buyers should check.
Published October 5, 2026
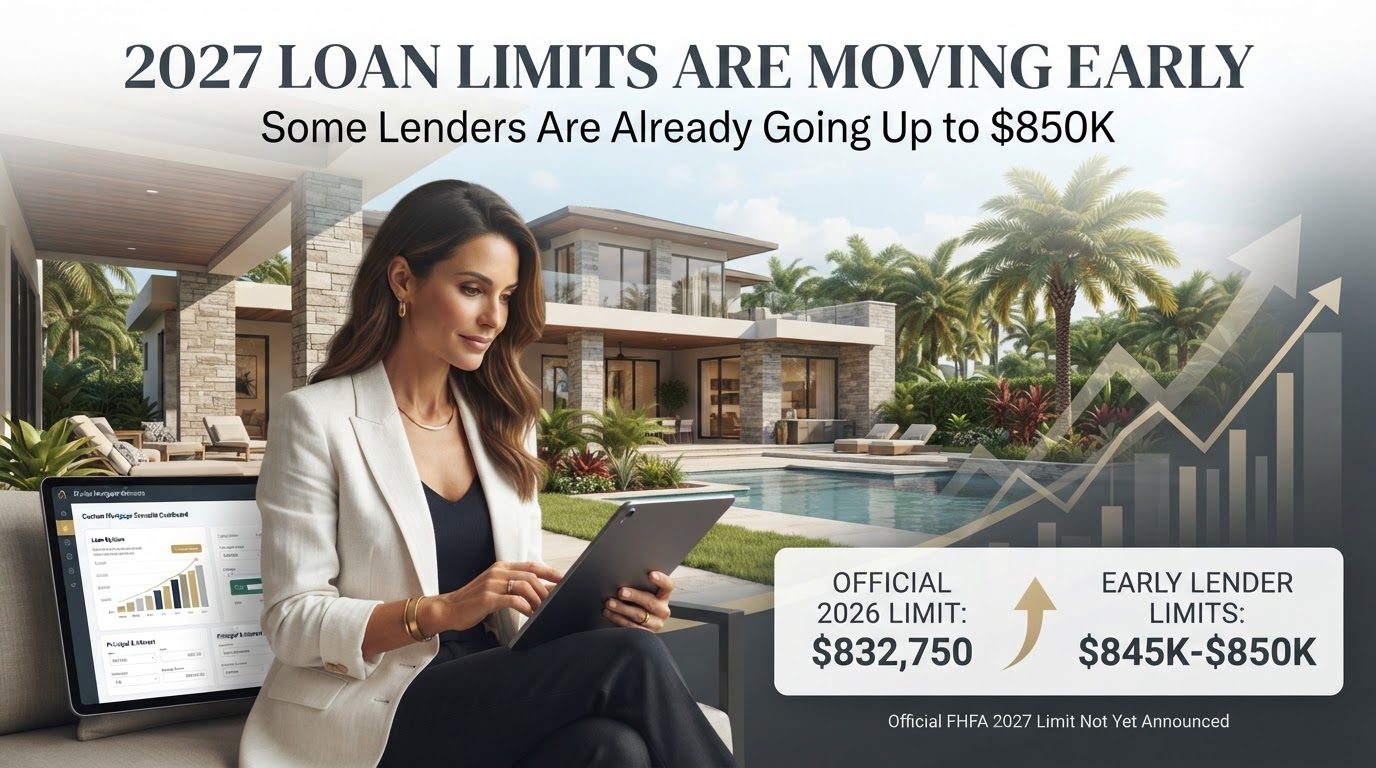
As of October 6, 2026, FHFA has not announced the official 2027 conforming loan limits. The official 2026 baseline remains $832,750 for a one-unit property in most of the country. However, some lenders have already introduced their own early 2027 limits between $845,000 and $850,000, potentially giving certain Florida buyers additional conventional financing room before the official update.
That does not mean $850,000 is the official new federal conforming limit. The distinction matters.
What is the official conforming loan limit today?
For 2026, the Federal Housing Finance Agency set the national baseline conforming loan limit for a one-unit property at $832,750. The maximum one-unit ceiling for qualifying high-cost areas is $1,249,125.
FHFA sets conforming loan limits because Fannie Mae and Freddie Mac are legally restricted in the mortgage balances they may purchase under the conforming framework. Loans above the applicable FHFA limit are generally considered jumbo loans rather than conforming mortgages.
For many Florida buyers, especially in South Florida, that line can materially affect which loan programs, underwriting standards and pricing structures are available.
Has FHFA announced the official 2027 limit?
No. As of October 6, FHFA's conforming-loan-limit page still lists the 2026 limits as the current official limits.
FHFA's annual adjustment is based on changes in U.S. home prices under the formula established by the Housing and Economic Recovery Act. For 2026, for example, FHFA raised the baseline from $806,500 to $832,750 after its home-price index showed a 3.26% annual increase.
The official 2027 calculation has not yet been published. So when you see "2027 conforming limit is $850,000," that statement is premature. What we actually have today are lender-specific early limits.
Why are lenders already offering higher limits?
Mortgage lenders sometimes raise their internal conventional loan ceilings before FHFA publishes the following year's official limit. They are essentially making an early operational decision based on where they believe the official limit is likely to land, while managing the secondary-market and delivery risk internally.
This is not unusual. Several lenders did the same thing ahead of the 2026 FHFA announcement. But borrowers should understand that an early lender limit and an official FHFA conforming limit are not the same thing.
Which lenders have announced early 2027 limits?
Here is the current picture from lenders that have publicly announced higher limits:
| Source | Early one-unit conventional limit | Increase over official 2026 baseline |
|---|---|---|
| Official FHFA 2026 limit | $832,750 | — |
| CrossCountry Mortgage | $845,000 | +$12,250 |
| United Wholesale Mortgage | $847,440 | +$14,690 |
| Pennymac | $850,000 | +$17,250 |
CrossCountry Mortgage announced its $845,000 Early Bird limit on September 10. United Wholesale Mortgage announced an estimated $847,440 one-unit conventional limit on September 16 and explicitly stated that it was acting ahead of any official FHFA announcement. Pennymac raised its one-unit conventional ceiling to $850,000 for new locks beginning September 16, while clearly noting that the official 2027 limit will ultimately be determined by FHFA.
That difference among lenders is exactly why buyers and Realtors should not treat one advertised "2027 limit" as universal.
Can I actually get an $850,000 conventional loan today?
Potentially — with a lender or investor that currently supports an early-limit program and if the complete mortgage satisfies that lender's requirements. But this should not be translated into "Every conventional lender now allows $850,000." They do not.
One lender may currently stop at $845,000. Another may use $847,440. Another may allow $850,000. And another may still operate strictly under the official $832,750 baseline until FHFA announces the 2027 values.
Availability can also depend on property type, occupancy, loan-to-value, automated underwriting, mortgage insurance, transaction type, investor overlays, and the specific lender or channel. That makes lender selection unusually important for borrowers whose loan amount is right around the current cutoff.
A South Florida example
Suppose a buyer is purchasing a home for $890,000 and plans to put 5% down. The down payment would be $44,500, leaving a base loan amount of approximately $845,500.
Under the official 2026 baseline of $832,750, that loan exceeds the normal one-unit baseline limit. But under the current lender examples:
- CrossCountry's $845,000 early limit: approximately $500 too high.
- UWM's $847,440 early limit: potentially within the lender's early-limit range.
- Pennymac's $850,000 early limit: potentially within the lender's early-limit range.
That does not mean the borrower automatically qualifies. It simply demonstrates how a difference of a few thousand dollars in lender-specific limits can change which financing path deserves consideration.
Example is illustrative only. Loan eligibility, mortgage insurance, pricing, property approval, underwriting and maximum LTV requirements still apply.
Purchase price and loan amount are not the same thing
This is one of the biggest misunderstandings around conforming limits. The conforming loan limit is a limit on the loan amount. It is not a limit on the home's purchase price.
A buyer can purchase a home for more than $832,750 and still obtain a conforming-size mortgage if the down payment is large enough to bring the loan amount below the applicable limit. For example:
- Purchase price: $950,000
- 20% down payment: $190,000
- Loan amount: $760,000
That is well below the current official $832,750 one-unit baseline. So when a Realtor says "This house is above the conventional limit," the better question is "What loan amount will the buyer actually need?"
Why staying within an agency-style loan program may matter
Conforming and jumbo mortgages are different lending channels. Jumbo loans can have their own credit standards, reserve requirements, debt-to-income limits, appraisal requirements, documentation, down-payment rules, and pricing.
That does not mean jumbo financing is automatically worse. In fact, some jumbo programs can price very competitively for certain strong borrowers. The point is that crossing a loan-limit threshold can change the menu of available options. A borrower at $840,000 should therefore compare an early-limit conventional option versus a jumbo option rather than assume one is automatically cheaper or easier.
Why this matters with mortgage rates back above 7%
Freddie Mac reported that the national average 30-year fixed mortgage rate was 7.28% on October 1, 2026, up from 7.03% the previous week. The 15-year fixed average was 6.60%.
These are broad national survey averages based on mortgage applications — not individual Florida mortgage quotes. But in a higher-rate environment, buyers purchasing in the upper conventional price range often pay closer attention to every part of the structure: down payment, loan amount, mortgage insurance, lender credits, seller concessions, rate, and whether the loan falls into a conforming-style or jumbo channel. That is why the early-limit movement is more than an industry technicality. It can influence how an offer is structured.
Realtors should confirm the lender's limit before writing the offer
This is especially important if a preapproval relies on one of these early limits. Imagine a buyer is approved around an $848,000 loan amount. One lender may have a program that supports it. Another lender may not. If the buyer switches lenders after going under contract, the financing structure could change.
For Realtors, I would confirm:
- What exact loan amount is the preapproval based on?
- Is the lender using an official 2026 limit or an early 2027 lender-specific limit?
- Is the early limit available for this property and occupancy type?
- What happens if the official FHFA number comes in below the lender's early limit?
These are good questions before a financing contingency is tested.
What happens when FHFA publishes the real 2027 limits?
Once FHFA publishes the official 2027 values, Fannie Mae, Freddie Mac and mortgage lenders will update their systems around those limits. That can involve automated underwriting updates. Pennymac's September announcement specifically warns its correspondent sellers that certain loans may need to be run through the automated underwriting system again after the official limits are released.
So buyers using an early-limit program should understand that the lender's implementation requirements matter. This is not a reason to avoid the programs. It is a reason to use a lender that understands the transition.
Could the official 2027 limit be lower than $850,000?
Yes. Until FHFA publishes the actual number, nobody should state the 2027 national baseline as a certainty. The lenders themselves acknowledge that. Pennymac labels $850,000 as an increased internal conventional limit and specifically says the official 2027 conventional loan limit will be determined by an upcoming FHFA announcement. UWM calls its numbers estimated 2027 conforming loan limits. CrossCountry similarly describes its $845,000 ceiling as an Early Bird program launched before the official FHFA announcement.
That is the appropriate way to present this to consumers.
What about two-, three- and four-unit properties?
Some early-limit programs are also increasing limits for multi-unit properties. For example, UWM currently lists two-unit at $1,085,059, three-unit at $1,311,535, and four-unit at $1,630,005. Pennymac currently lists two-unit at $1,088,350, three-unit at $1,315,500, and four-unit at $1,634,950.
Again, these are lender-specific early limits — not the official FHFA 2027 numbers. For a South Florida buyer considering a duplex, triplex or fourplex, though, that additional capacity may be worth comparing.
Does this change FHA limits?
No. Pennymac explicitly states that its early conventional limits apply to conventional loans only and that government loan limits remain unchanged. FHA loan limits are governed separately through HUD. So a lender increasing its conventional loan ceiling to $850,000 does not mean the FHA loan limit also jumped to $850,000. The same principle applies when comparing other government-backed financing. Do not mix the programs.
Does this automatically change Fannie Mae and Freddie Mac underwriting today?
Not in the same way an official FHFA announcement would. These are lender-specific programs being offered before the official annual limit update. Pennymac's guidance is a good example: it allows certain loans above the official current limit under its early program, but it also lays out special automated-underwriting and appraisal treatment during the transition.
This is another reason borrowers should not assume "My lender said $850,000, so $850,000 is now the Fannie Mae limit." It is not.
Could putting slightly more money down make more sense?
Sometimes. Suppose a borrower needs a loan amount of $852,000. That is above all three early-limit examples discussed here. The borrower could consider adding enough down payment to reduce the loan into an early conventional range, comparing a jumbo loan, restructuring seller credits, or considering another appropriate financing option.
The best answer depends on cash reserves, pricing and the borrower's long-term financial goals. I would not advise draining liquidity just to say the mortgage is "conventional." The math needs to make sense.
Why this can be especially useful in Miami-Dade, Broward and Palm Beach
South Florida routinely produces purchase scenarios around or above the national baseline loan limit. That means relatively small changes in the financing amount can determine whether a borrower sits just under or just above a lender's agency threshold.
For a buyer purchasing an $850,000 to $1 million property, I would not simply ask "Do you qualify?" I would also look at what down payment creates the strongest financing tier. A slightly different loan amount may open another set of options. That does not always mean putting more money down. It means knowing where the thresholds are before structuring the offer.
What I'm telling buyers right now
If your proposed conventional loan amount is above $832,750 but around $850,000, do not immediately assume you need a jumbo mortgage. Ask whether your lender has implemented an early 2027 conventional limit. Then compare that option against jumbo financing.
If your loan amount is comfortably below $832,750, this development probably does not change your financing today. And if your loan is substantially above $850,000, the early limits may not solve the gap. The biggest opportunity is for borrowers sitting right around the current threshold.
Buying near the conventional/jumbo cutoff?
Before changing your down payment or assuming you need a jumbo mortgage, let's compare the official 2026 limit, current early 2027 lender limits and jumbo options using your actual purchase price and loan amount.
Early loan limits, underwriting, rates, pricing and program availability vary by lender and are subject to change. The figures discussed above are lender-specific programs offered before FHFA's official 2027 announcement. This article is educational and does not constitute a commitment to lend, guarantee of approval, guarantee of program availability or individual mortgage-rate quote.
Frequently Asked Questions
What is the official 2027 conforming loan limit?▾
As of October 6, 2026, FHFA has not yet published the official 2027 conforming loan limits. The official current baseline remains $832,750 for a one-unit property in most U.S. areas.
Is $850,000 the new conforming loan limit?▾
Not officially. Pennymac currently allows up to $850,000 under its early conventional limit program, but it clearly states that the official 2027 limit will be determined by FHFA.
Can I get more than $832,750 with a conventional lender today?▾
Potentially. Certain lenders have already implemented early-limit programs ranging from $845,000 to $850,000 for one-unit conventional loans, subject to lender and borrower eligibility.
Does every lender allow $850,000?▾
No. Current publicly announced early limits vary by lender, and some lenders may still use the official 2026 limit.
Is a home above $832,750 automatically a jumbo purchase?▾
No. The limit applies to the mortgage amount, not the sales price. A buyer can purchase a more expensive home and remain below the applicable loan limit by making a sufficient down payment.
Is a jumbo mortgage always more expensive than conventional financing?▾
No. Jumbo pricing and underwriting vary by borrower, lender and market conditions. In some scenarios a jumbo loan may be competitive or preferable.
Do these early limits apply to FHA?▾
Not automatically. Government loan limits operate under separate rules. Pennymac explicitly states its current early-limit increase is for conventional financing and that government limits remain unchanged.
What happens when FHFA announces the official 2027 limit?▾
Lenders and automated underwriting systems will transition to the official figures. Some early-limit loans may require updated underwriting or other lender-specific review.
Authoritative Sources
- FHFA — Current Conforming Loan Limit Values
- FHFA — Official 2026 Conforming Loan Limit Announcement
- UWM — Early 2027 Conforming Loan Limits, September 16, 2026
- Pennymac — Increased Conventional Loan Limits, September 16, 2026
- CrossCountry Mortgage — $845,000 Early Bird Limit, September 10, 2026
- Freddie Mac — Current Mortgage Rate Survey
This is not a commitment to lend. All loans are subject to credit approval, property approval, program guidelines, and applicable terms. Programs, rates, terms, and conditions are subject to change without notice. Not all applicants will qualify. Equal Housing Opportunity.
Angel Taipale, NMLS #1736690 — Bright Horizon Lending Inc., NMLS #2565670. Verify on NMLS Consumer Access
More from Market Updates
Will Mortgage Rates Drop After the September Fed Meeting? What Florida Buyers Should Know
The Federal Reserve meets September 15–16, 2026. Learn why a Fed decision does not automatically change mortgage rates and what Florida buyers should watch.
ReadFlorida Home Insurance Is Changing the Mortgage Payment: What Buyers Need to Know in 2026
Homeowners insurance is becoming a major part of the mortgage payment. See what new 2026 data means for Florida buyers and why shopping insurance early can protect your qualification.
Read