HELOC & Equity
HELOC vs. Cash-Out Refinance in Florida: Which Makes Sense in 2026?
Compare a HELOC vs. cash-out refinance in Florida, including how each affects your first mortgage, payment, rate risk and access to home equity.
Published September 14, 2026
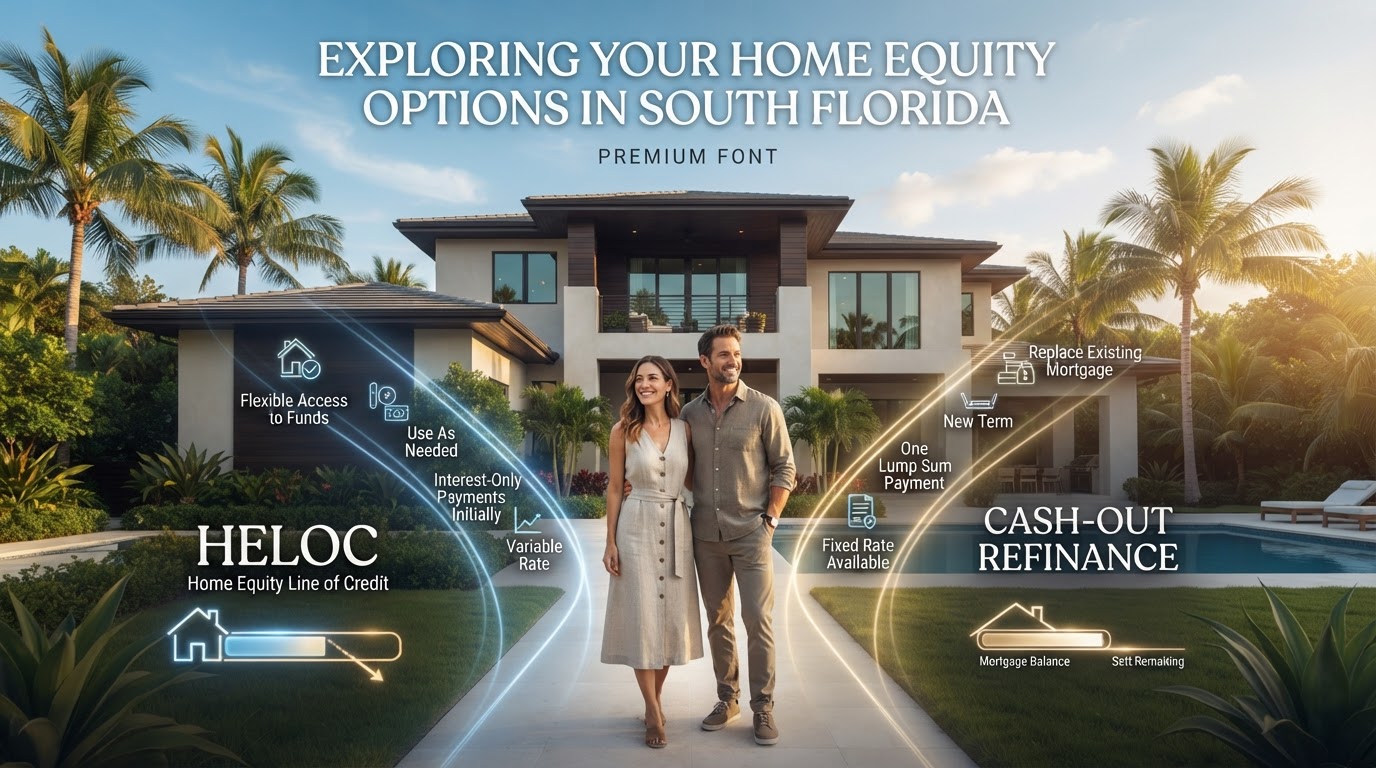
A HELOC lets you access home equity while generally leaving your existing first mortgage intact, while a cash-out refinance replaces the existing mortgage with a new, larger first mortgage. In 2026, that distinction matters: HELOC balances have risen for 17 straight quarters as homeowners increasingly use second-lien equity products. The better option depends on your current first-mortgage rate, amount needed, timeline, costs and tolerance for variable rates.
Homeowners are tapping equity again
Home-equity borrowing has been quietly increasing. The Federal Reserve Bank of New York reported that outstanding HELOC balances increased by another $13 billion in the second quarter of 2026, reaching $459 billion. That's $142 billion above the low reached in the first quarter of 2022.
Q2 2026 was also the 17th consecutive quarter in which HELOC balances increased, and total HELOC credit limits grew another $19 billion during the quarter.
This trend makes sense when you consider the choice many homeowners face. They may have significant home equity but don't necessarily want to replace their existing first mortgage just to access some of it. That brings us to one of the most important homeowner-financing comparisons in today's market: HELOC or cash-out refinance?
What is a HELOC?
A Home Equity Line of Credit, or HELOC, is a revolving line of credit secured by your home. The Consumer Financial Protection Bureau describes a HELOC as an open-end credit line that allows a homeowner to borrow repeatedly against available home equity during the applicable draw period.
Think of it less like receiving one large mortgage check and more like having access to an approved credit line. Depending on the actual HELOC terms, you may be able to:
- draw funds when needed;
- repay some or all of the balance;
- restore available credit as payments are made;
- and draw again during the permitted draw period.
That flexibility can be useful when you don't need all of the money at once. For example, a homeowner renovating a house may need $20,000 now, another $30,000 several months later and additional funds when the next phase begins. A line of credit can fit that cash-flow pattern differently than receiving one lump sum upfront.
The exact draw, repayment and minimum-balance rules vary by lender and product. CFPB notes that some HELOCs require minimum draws, minimum balances or an initial advance.
What is a cash-out refinance?
A cash-out refinance works differently. Instead of adding a separate credit line behind the existing first mortgage, the homeowner refinances into a new, larger first mortgage and receives part of the new loan proceeds as cash after paying off the existing mortgage and applicable transaction costs.
CFPB explains the core distinction this way: a cash-out refinance replaces the original mortgage, while home-equity products such as HELOCs generally leave the existing first-lien mortgage intact.
That difference is extremely important. Suppose you owe $300,000 on your current first mortgage and need $75,000 for a major project. With a HELOC structure, you might keep the existing $300,000 first mortgage and add a separate line for the equity you actually need. With a cash-out refinance, you would instead replace the original mortgage with a larger new first mortgage sufficient to pay off the old loan and provide the approved cash proceeds.
Neither structure is automatically better. The question is what happens to the entire financing picture.
Why your existing mortgage rate matters
This is one of the first things I look at when a Florida homeowner asks about accessing equity. Freddie Mac reported that the national average 30-year fixed mortgage rate was 6.76% as of September 10, 2026. That is a broad national purchase-market average—not a cash-out refinance quote and not a rate available to every borrower.
Now imagine a homeowner already has a significantly lower fixed rate on a sizable first mortgage. Replacing that mortgage just to obtain a relatively smaller amount of cash could mean repricing the entire first-mortgage balance at current refinance terms.
That's when a HELOC or another second-lien structure deserves serious consideration. Instead of asking only: "Which product has the lower interest rate?" I prefer asking: "How much debt is actually being subjected to the new rate?" That is a much better comparison.
A simple way to think about it
Imagine a homeowner has:
- Existing first mortgage: $300,000
- Equity needed: $75,000
With a HELOC, the existing $300,000 mortgage generally remains in place and the new financing applies to the equity line. With a cash-out refinance, the existing first mortgage is paid off and replaced with a new, larger mortgage.
So even if a HELOC has a higher stated interest rate than a new first mortgage, it does not automatically mean the cash-out refinance produces the better overall outcome. You have to compare the cost of financing $75,000 separately with the cost of refinancing the entire mortgage balance plus the desired cash-out amount. That's why comparing rate alone can be misleading.
Where a HELOC can make sense
A HELOC deserves consideration when a homeowner:
- Has a first-mortgage rate they would prefer not to replace. This is probably the most important 2026 use case.
- Doesn't need all the money immediately. A line of credit allows borrowers to draw funds as needed, subject to the plan's terms.
- Wants an available source of liquidity. Some homeowners establish a line for planned improvements, future investment opportunities, education costs or other major expenses without immediately borrowing the entire approved amount.
- Expects to repay the borrowed amount relatively quickly. The right structure depends on rates and terms, but flexibility can be useful when the borrowing period is expected to be shorter.
- Wants to preserve the existing first mortgage. A HELOC is generally a second mortgage when an existing first mortgage remains outstanding.
Where a cash-out refinance can make more sense
Cash-out refinancing shouldn't be dismissed simply because HELOC use is increasing. A cash-out structure may deserve consideration when:
- The current first mortgage isn't especially attractive. If the existing rate and terms are similar to—or less favorable than—available refinance options, protecting the old mortgage may have less value.
- The homeowner wants one mortgage payment rather than two obligations. A cash-out refinance consolidates the financing into a new first mortgage rather than maintaining the original first plus a HELOC.
- The homeowner needs a large amount of cash upfront. For certain scenarios, borrowing the needed equity in one transaction may be more appropriate than maintaining a revolving line.
- Fixed-rate certainty is particularly important. Many cash-out first mortgages use fixed-rate structures, while HELOCs commonly have variable rates.
Again, loan availability and actual terms vary.
The biggest HELOC tradeoff: variable rates
The flexibility of a HELOC comes with an important risk. CFPB says HELOCs usually have variable interest rates, meaning the rate—and potentially the payment—can change. Some HELOCs also allow a borrower to convert part or all of an outstanding balance into a fixed-rate segment, but availability and terms depend on the product.
Variable HELOC rates generally involve a publicly available index plus a lender margin. That means homeowners need to understand more than the introductory or starting rate. Ask:
- What index is being used?
- What is the margin?
- How often can the rate change?
- Is there a floor?
- Is there a lifetime rate cap?
- Is there a fixed-rate conversion feature?
- Are there fees associated with converting?
- What happens when the draw period ends?
These questions are at least as important as the initial advertised rate.
What happens when the HELOC draw period ends?
This catches some homeowners by surprise. A HELOC generally has a period during which the borrower can access the line. After that comes the repayment period. CFPB says the borrower typically can no longer make new draws during repayment, and payments may increase substantially as the balance is amortized. Some plans may even require a large payment when the draw period expires.
So I would never evaluate a HELOC only by asking: "What is my payment today?" We also need to ask: "What could my payment look like later?"
Can you pay a HELOC down and draw from it again?
Often, yes, during the draw period. CFPB explains that HELOC available credit can generally replenish as the borrower repays the balance, similar in concept to revolving credit. But the specific agreement controls. Some products have: minimum advance requirements, minimum outstanding balances, inactivity fees, annual fees, early cancellation fees, or other restrictions.
Another important point: access isn't always guaranteed forever. CFPB notes that lenders may restrict or freeze additional draws in certain circumstances, including a significant decline in the home's value or certain adverse changes in the borrower's financial circumstances. That's why a HELOC should not automatically be treated like an emergency cash account that can never change.
What about closing costs?
Both structures can have costs. A cash-out refinance can involve costs associated with originating an entirely new first mortgage. A HELOC can also include fees. CFPB identifies possible HELOC charges such as: application fees, origination fees, appraisal or valuation costs, title-related costs, annual fees, inactivity fees, early termination fees, and fixed-rate conversion fees.
Some lenders or HELOC programs may absorb or waive certain costs. Others may not. Instead of comparing products based on an advertisement saying "no closing costs," compare the actual disclosures and ask whether waived costs can be recaptured through an early-closure provision.
HELOC vs. home equity loan
These products are related, but they're not identical. A traditional home equity loan generally provides a fixed amount of money upfront. A HELOC provides access to a revolving line from which the homeowner can draw repeatedly, subject to the program terms. CFPB notes that home equity loans can use fixed or adjustable rates, while HELOCs commonly use adjustable rates and vary based on the outstanding balance.
So homeowners actually have three broad equity-access strategies worth comparing:
- HELOC — Revolving second-lien line.
- Home equity loan — Typically a lump-sum second lien.
- Cash-out refinance — New first mortgage replacing the existing mortgage.
The best choice depends on what the homeowner is trying to accomplish.
Why HELOC borrowing is increasing
The latest Federal Reserve Bank of New York numbers show this is more than a marketing trend. HELOC balances have now climbed for 17 consecutive quarters and reached $459 billion by the end of June 2026.
Separate mortgage-market research from ICE also found that homeowners withdrew $116 billion through second-lien products during 2025, the largest annual second-lien volume since 2007. ICE estimated homeowners were still holding nearly $17 trillion of total home equity at the time, about $11 trillion of which it classified as tappable.
One reasonable explanation for the shift is the mortgage-rate environment. Homeowners who already have favorable fixed first mortgages may prefer accessing a smaller portion of their equity separately rather than replacing the original mortgage. That doesn't make second liens universally cheaper. It means the comparison has changed.
What about using equity to consolidate debt?
This is where I think homeowners need to be particularly careful. A homeowner may see a much higher credit-card interest rate and think: "I'll just pay all of this off with my home equity." Mathematically, that can sometimes improve monthly cash flow. But you're also changing the nature of the debt.
CFPB's research found that paying off other bills and debts has historically been one of the most common uses of cash-out refinance proceeds. The agency also emphasizes that converting unsecured debt into mortgage debt can increase the risk to the homeowner because the new debt is secured by the home.
That doesn't mean debt consolidation is always wrong. It means the strategy should include a plan for why the debt accumulated and how to prevent rebuilding those balances afterward. Lowering the monthly payment without changing the underlying spending pattern can simply move debt from one place to another.
Florida homeowners should consider the property too
Home equity is determined by more than what you originally paid for the house. The lender will evaluate the property value and existing liens when determining available equity and combined loan-to-value. That matters in South Florida, where property types can also affect the available options.
A single-family primary residence may have different HELOC choices than: a condominium, an investment property, a second home, a multi-unit property, or a non-warrantable condo. Lender eligibility can also vary based on credit, income documentation, occupancy and loan amount. So I wouldn't assume a HELOC advertised online automatically applies to every Florida property.
One issue to know before taking a HELOC: future refinancing
There is another planning issue homeowners sometimes miss. A HELOC can affect a later refinance of the first mortgage. CFPB explains that a homeowner may need approval from the HELOC lender to refinance the first mortgage while keeping the HELOC in place. If the second-lien holder will not agree, the homeowner may need to pay off the HELOC in connection with the refinance.
That's not necessarily a reason to avoid a HELOC. It is a reason to think beyond the immediate cash need. If you believe you're likely to refinance your first mortgage soon, the sequencing of the transactions matters.
What I would compare before choosing either option
When I review this with a homeowner, I don't start with "Which lender has the lowest advertised rate?" I start with these questions:
- What is your current first-mortgage balance and rate? The more valuable that existing mortgage is, the stronger the argument may become for preserving it.
- How much equity do you actually need? Needing $50,000 is very different from needing $400,000.
- Do you need the money all at once? That helps determine whether revolving access has value.
- How quickly do you expect to repay it? A short-term equity need and a 20-year borrowing plan shouldn't automatically use the same product.
- How comfortable are you with variable-rate risk? A payment that changes may not fit every budget.
- What are the total costs? Rate, margin, fees, closing costs and the amount of debt being refinanced all matter.
- What are you using the money for? An improvement that adds utility or value, an investment opportunity, debt consolidation and discretionary consumption all deserve different conversations.
A Florida homeowner example
Imagine you bought or refinanced several years ago and have a first mortgage you are happy with. Now you want funds for: a kitchen renovation, hurricane-impact windows, a new roof, a pool or outdoor project, tuition, business needs, debt restructuring, or an investment-property down payment.
The question shouldn't automatically be: "Can I cash out?" It should be: "What is the least disruptive and most cost-effective way to access the amount I actually need?" Sometimes that's a HELOC. Sometimes it's a home equity loan. Sometimes it's a cash-out refinance. And sometimes the right answer is not to borrow against the house at all. That's the comparison worth making.
Have equity but don't want to automatically replace your first mortgage?
I can compare a HELOC, home-equity loan and cash-out refinance side-by-side using your current mortgage balance, rate, equity and actual cash need. Let's compare your options →
Side-by-side comparison
| Feature | HELOC | Cash-Out Refinance |
|---|---|---|
| Existing first mortgage | Generally stays | Replaced |
| Funds | Draw as needed | Lump sum |
| Rate structure | Usually variable | Often fixed-rate options |
| Borrow again | During draw period, subject to terms | No |
| Payment | Based on HELOC terms/balance | New first-mortgage payment |
| Key consideration | Variable-rate risk | Repricing entire first mortgage |
| Best comparison | Amount actually needed | Entire new mortgage structure |
Program terms and qualification vary. This comparison is educational.
Bottom line
HELOC use is rising again for a reason. As of Q2 2026, U.S. HELOC balances had increased for 17 straight quarters to $459 billion.
For Florida homeowners, however, the takeaway shouldn't be: "Everyone should get a HELOC." It should be: "Don't refinance your entire mortgage until you've compared what you're giving up."
If your existing first mortgage has attractive terms and you only need a portion of your home equity, a HELOC or home-equity loan deserves comparison. If your existing mortgage no longer fits your needs, a cash-out refinance may produce a better overall structure. Compare the total strategy—not just one advertised rate.
Home-equity and refinance programs, rates, credit limits, draw terms, fees and qualification vary by lender, borrower and property. Borrowing against home equity places your property at risk if payments are not made as agreed. This information is educational and does not constitute a commitment to lend, financial advice or a guarantee of loan approval or terms.
Frequently Asked Questions
Is a HELOC the same as refinancing my mortgage?▾
No. A HELOC is typically an additional lien that leaves an existing first mortgage intact. A cash-out refinance replaces the original first mortgage with a new, larger mortgage.
Can I repay a HELOC and borrow the money again?▾
Generally, available credit can replenish as the outstanding balance is repaid during the draw period, subject to your specific HELOC agreement.
Are HELOC rates fixed?▾
Usually not. CFPB says HELOCs generally have variable interest rates, although some plans allow a portion of the balance to be converted to a fixed-rate structure.
Why would I use a HELOC instead of a cash-out refinance?▾
One potential reason is to access equity without replacing an existing first mortgage whose rate or terms you want to preserve. The right choice depends on the complete financing comparison.
Is a HELOC always cheaper?▾
No. A HELOC may carry a higher rate, variable-rate risk and various fees. The proper comparison includes the amount borrowed, current first mortgage, rates, terms, closing costs and expected repayment period.
Can I open a HELOC and leave it unused?▾
Some plans permit this, but others may have initial-draw requirements, inactivity fees, minimum balances or other conditions. Review the actual HELOC agreement.
Can my HELOC lender stop me from drawing more money?▾
In certain circumstances, yes. CFPB notes that lenders may limit additional access if the home's value falls significantly or certain financial circumstances deteriorate.
Does a HELOC affect a future mortgage refinance?▾
It can. You may need the HELOC lender to agree to remain in a subordinate position, or the HELOC may need to be paid off as part of the refinance.
Authoritative Sources
- Federal Reserve Bank of New York — Q2 2026 Household Debt and Credit Report
- CFPB — What Is a HELOC? (Updated August 2026)
- CFPB — HELOC vs. Home Equity Loan
- CFPB — Cash-Out Refinance Research
- CFPB — How a HELOC Can Affect a Future Refinance
- Freddie Mac — Current Mortgage Rate Survey
- ICE — March 2026 Mortgage Monitor: Home Equity Extraction
This is not a commitment to lend. All loans are subject to credit approval, property approval, program guidelines, and applicable terms. Programs, rates, terms, and conditions are subject to change without notice. Not all applicants will qualify. Equal Housing Opportunity.
Angel Taipale, NMLS #1736690 — Bright Horizon Lending Inc., NMLS #2565670. Verify on NMLS Consumer Access