HELOC & Equity
Can You Remove PMI With Home Appreciation? New Fannie Mae Rule for 2026
Some homeowners with a Fannie Mae conventional mortgage may remove PMI based on the home's current value, not just the original price. See the new September 16 servicer rule and LTV thresholds.
Published September 28, 2026
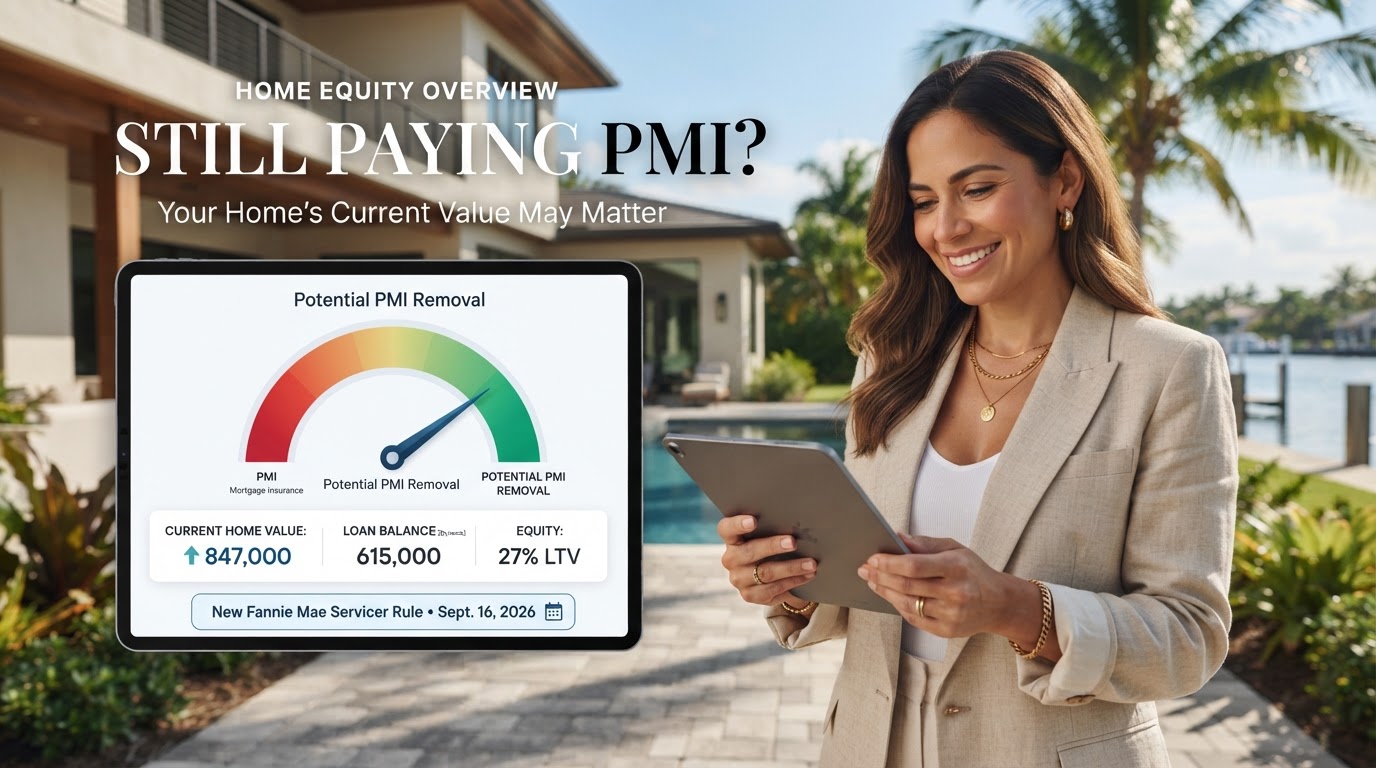
Yes—some homeowners with a Fannie Mae conventional mortgage may be able to remove private mortgage insurance based on the home's current value, not just the original purchase price. On September 16, 2026, Fannie Mae began allowing servicers to proactively contact potentially eligible borrowers. Current-value LTV, loan seasoning, payment history and an approved property valuation still determine whether PMI can actually be terminated.
For Florida homeowners who already have an attractive first-mortgage rate, this is worth checking before assuming a refinance is necessary just to get rid of mortgage insurance.
What changed on September 16?
Fannie Mae issued Lender Letter LL-2026-07 on September 16, 2026. The change is simple but meaningful.
Previously, under Fannie Mae's servicing rules, a homeowner seeking PMI termination based on the current market value of the property generally had to initiate the request. Fannie Mae now permits mortgage servicers to proactively identify and contact borrowers whose loans may be close to or already meet the current-value LTV requirements for mortgage-insurance termination. The policy became effective immediately.
That does not mean the servicer automatically removes your PMI. And it does not mean Fannie Mae lowered the equity requirements. The change is primarily about who may start the conversation. That distinction matters.
Why homeowners may be paying PMI in the first place
Private mortgage insurance, commonly called PMI, is generally associated with conventional mortgages where the borrower puts down less than 20%. PMI protects the lender or investor—not the homeowner—against certain losses if the borrower defaults.
It can be useful because it allows qualified buyers to purchase a home without waiting until they have accumulated a 20% down payment. But PMI does not necessarily remain forever. There are several different ways it can eventually end. And one of those pathways considers what the property is worth today.
There are two different equity calculations homeowners should understand
This is where PMI conversations often get confusing.
PMI removal based on the original value
Federal law gives many borrowers the right to request cancellation when the mortgage balance reaches 80% of the home's original value, subject to applicable requirements. PMI generally must terminate automatically when the loan is scheduled to reach 78% of the original value, assuming the borrower is current. Federal law also provides a final termination point at the midpoint of the original amortization schedule in applicable circumstances.
For a purchase mortgage, the "original value" generally means the lower of the original purchase price or the original appraised value.
But Fannie Mae also has another route.
PMI removal based on the current value
Instead of waiting for the mortgage balance to decline according to the original value, certain Fannie Mae borrowers can request termination using an approved valuation of what the property is worth now. That means home-price appreciation—or qualifying improvements you have made to the property—can potentially matter. This is the route affected by Fannie Mae's September 16 policy change.
What LTV does Fannie Mae require based on current value?
For a one-unit primary residence or second home, Fannie Mae's current servicing requirements generally use the following thresholds:
| Loan age | Current-value LTV generally required |
|---|---|
| Less than 2 years | Generally not eligible based solely on appreciation, subject to the substantial-improvement exception |
| 2 to 5 years | 75% or less |
| More than 5 years | 80% or less |
Fannie Mae also allows its normal two-year seasoning requirement to be waived in certain cases where borrower-made property improvements increased the home's value. In that situation, the LTV generally must be 80% or less based on current value.
For a one- to four-unit investment property or a two- to four-unit primary residence, Fannie Mae's current-value requirement is generally 70% LTV or less, with the mortgage seasoned more than two years.
These are Fannie Mae servicing rules; the mortgage servicer must still evaluate the actual loan and applicable requirements.
A Florida homeowner example
Suppose a homeowner purchased a property three years ago and still has PMI.
- Current mortgage balance: $295,000
- Suppose the property valuation ordered through the applicable servicing process supports a current value of: $410,000
- The loan-to-value ratio would be approximately: 72%
Because the mortgage is between two and five years old, that is below Fannie Mae's 75% current-value threshold for an eligible one-unit primary residence. That does not mean PMI disappears automatically. The borrower must also satisfy the payment-history requirements and the servicer must complete the required valuation and eligibility review. But that is exactly the type of scenario worth investigating.
Example is illustrative only and does not represent a property valuation, approval or guarantee of mortgage-insurance termination.
What if I renovated the house?
This is one of the most useful parts of the rule for Florida homeowners who have substantially improved their property. Fannie Mae says the normal two-year seasoning requirement may be waived when improvements made by the borrower increased the property's value. Examples Fannie Mae identifies as improvements can include renovations that substantially improve marketability or extend the useful life of the home, such as kitchen renovations, bathroom renovations or added square footage. Routine maintenance or repairs that simply keep the home functional are not treated the same way.
So replacing a broken appliance is not the same as completing a major kitchen renovation. Likewise, normal roof maintenance is different from a substantial improvement that materially affects market value. The servicer evaluates the documentation and valuation.
Do I need an appraisal to remove PMI?
For Fannie Mae's current-value route, a property valuation is required through the servicing process. Fannie Mae's current servicing procedure states that a one-unit property generally requires an interior and exterior broker price opinion, or an appraisal where applicable. Two- to four-unit properties require an interior and exterior appraisal through Fannie Mae's servicing solution.
Current Fannie Mae servicing charges listed for these valuations are:
| Valuation | Current listed cost |
|---|---|
| BPO | $190 |
| Restricted appraisal — one unit | $450 |
| Appraisal — two to four units | $750 |
Fannie Mae states that the borrower is responsible for the applicable current-value valuation cost. The important point is that you generally should not order your own random appraisal first and assume your servicer has to use it. Contact the servicer and follow its approved PMI-termination process.
Zillow or an online estimate is not enough
An online home-value estimate may help you decide whether it is worth calling your mortgage servicer. But Fannie Mae's current-value cancellation requirements use a valuation obtained through the authorized servicing process. So if a website says your house is worth $650,000, that does not by itself establish the value the servicer will use. I would use consumer estimates as a screening tool, not as the final PMI decision.
Your payment history also matters
Equity by itself is not enough. For current-value PMI termination, Fannie Mae generally requires the mortgage to:
- be current when the termination request is evaluated;
- have no payment 30 days or more past due during the previous 12 months; and
- have no payment 60 days or more past due during the previous 24 months.
If a loan was assumed by a new borrower, Fannie Mae generally requires the new borrower to have a 24-month payment history before current-value termination can occur.
This is why I would not tell a homeowner: "Your Zestimate shows 25% equity, so your PMI can come off." That skips several important steps.
What exactly does the new Fannie Mae rule do?
Here is the clearest way to understand the September change.
Before September 16: A homeowner could potentially qualify for PMI termination based on current value—but generally needed to know enough to ask the servicer.
Beginning September 16: Fannie Mae now allows the servicer to identify loans that may meet the criteria and proactively contact those borrowers with information about the actions required to terminate mortgage insurance.
What did not change: The servicer still has to evaluate current LTV, mortgage seasoning, payment history, property valuation and the other applicable requirements. So a letter or email from the servicer saying you may be eligible is not the same thing as final PMI cancellation.
Do you have to wait for the servicer to contact you?
No. If you think your conventional mortgage may qualify, you can still contact your mortgage servicer yourself. The September change allows proactive outreach; it does not remove the borrower's ability to request an evaluation.
A useful call to your servicer is: "I would like to know whether my loan is eligible for mortgage-insurance termination based on the current value of my property." Ask specifically what their process requires and whether the loan is owned by Fannie Mae.
How do I know whether Fannie Mae owns my mortgage?
Your mortgage company—the company receiving your monthly payment—is your servicer. That does not necessarily mean it is the investor that owns the mortgage. Fannie Mae offers an official consumer Loan Lookup Tool that allows homeowners to check whether Fannie Mae owns their loan. Fannie Mae notes that lookup results should still be confirmed with the mortgage company. Freddie Mac maintains a separate loan-lookup tool for Freddie Mac-owned mortgages.
For today's September policy change, the specific lender letter discussed here applies to Fannie Mae servicing.
Why this matters in the current mortgage-rate environment
There is another reason homeowners should understand PMI cancellation before immediately considering a refinance. Freddie Mac's latest weekly survey, published September 24, 2026, reported a national average 30-year fixed mortgage rate of 7.03%. That is a national conventional purchase-market average—not a refinance quote and not the rate every borrower would receive.
But many existing homeowners have first mortgages originated when rates were materially different. If the only goal is to remove PMI, replacing the entire first mortgage through a refinance may not make economic sense when an eligible PMI-termination request could potentially accomplish that goal without replacing the existing mortgage. That is a comparison I would make before touching the first lien.
Removing PMI is different from refinancing out of PMI
These are two separate strategies.
- PMI cancellation: You keep the existing mortgage. If your loan qualifies, the mortgage-insurance charge ends according to the applicable servicing rules.
- Refinance: The old mortgage is paid off and replaced with a new loan. The new loan could potentially avoid mortgage insurance if the new loan-to-value and program requirements allow it—but you are also changing the rate, term, costs and entire first-mortgage structure.
Your existing refinance resources make the important point that refinancing replaces the existing first mortgage and is not always the best solution when a homeowner has favorable existing terms. For someone whose only problem is PMI, I would check the servicing route first.
Does this new rule apply to FHA mortgage insurance?
No. This article is about conventional mortgage insurance on applicable Fannie Mae loans. FHA uses mortgage insurance premium, or MIP, and its cancellation rules are different.
For most FHA loans with case numbers assigned on or after June 3, 2013, annual MIP duration depends on the original LTV. Loans originated at 90% LTV or less generally carry annual MIP for 11 years, while loans above 90% generally carry it for the mortgage term. Home appreciation by itself does not convert FHA MIP into Fannie Mae-style current-value PMI cancellation. That distinction is important.
What about lender-paid mortgage insurance?
That can also be different. CFPB notes that the standard borrower PMI cancellation rules do not necessarily apply in the same way when the lender is paying the mortgage insurance. If you do not see a separate monthly PMI amount on your statement, that does not necessarily mean the original mortgage had no mortgage-insurance structure. Ask the servicer exactly how the loan was set up.
Still paying PMI on a conventional mortgage?
Before replacing your first mortgage, review your current balance, approximate home value and loan ownership. If the numbers are close, your mortgage servicer can tell you whether a current-value PMI review is available. Let's review your scenario →
What I would tell a Florida homeowner to do
If you bought with conventional financing and less than 20% down, particularly if you have owned the home for at least two years, I would check four things before considering a refinance solely to eliminate PMI:
- First, confirm the current mortgage balance.
- Second, get a reasonable estimate of the home's current market value—not as final proof, but to see whether the math is close.
- Third, determine whether Fannie Mae owns the loan.
- Fourth, call the servicer and ask specifically about mortgage-insurance termination based on current property value.
If the estimated numbers suggest your LTV is comfortably below the applicable threshold, paying for the approved valuation may be worth considering. If you are barely at the threshold, remember that the final servicer valuation—not your estimate—controls.
A practical South Florida point
In Miami-Dade, Broward and Palm Beach, two homes with similar purchase prices can have very different value trajectories depending on neighborhood, property condition, renovations, waterfront exposure, condominium status and the exact submarket. That is why I would not assume that simply owning a South Florida property for several years means you have enough equity to cancel PMI. Run the actual calculation.
And if you completed meaningful renovations, tell the servicer because Fannie Mae's rules specifically contemplate borrower-made improvements when evaluating certain seasoning exceptions.
What Realtors can do with this information
This is also a useful past-client conversation for Realtors. A buyer you helped two, three or four years ago may still be paying PMI even though their combination of principal reduction, market value and renovations may now put them near the applicable threshold. That does not mean an agent should tell the homeowner they qualify. A better message is: "Fannie Mae recently changed its rules so servicers may proactively identify homeowners who could qualify to remove PMI based on current value. If you bought with conventional financing and PMI, it may be worth asking your servicer whether your loan can be evaluated." That is accurate, useful and does not promise an outcome.
Bottom line
Fannie Mae's September 16 change does not create a brand-new right to remove PMI. What it does is make the opportunity easier to surface. Servicers may now proactively contact homeowners who appear close to Fannie Mae's current-value PMI termination thresholds, instead of waiting for every homeowner to discover the rule independently.
For Florida homeowners, the bigger lesson is this: If you have conventional PMI and your property value or equity has changed substantially, check whether you can remove the insurance before assuming you need to refinance your mortgage. You may find that the most valuable thing your equity can do today is not provide more debt. It may simply reduce the cost of the mortgage you already have.
Mortgage-insurance termination depends on loan ownership, property type, LTV, loan seasoning, payment history, valuation results, mortgage-insurance structure and servicer/investor requirements. Property values are not guaranteed, and an estimated home value does not establish eligibility. This article is educational and is not a commitment to lend, appraisal opinion, servicing decision or guarantee of PMI cancellation.
Frequently Asked Questions
Can home appreciation help me remove PMI?▾
Potentially. Fannie Mae allows mortgage-insurance termination based on an approved current property value when the loan satisfies applicable LTV, seasoning, payment-history and valuation requirements.
What changed with Fannie Mae PMI rules in September 2026?▾
Effective September 16, Fannie Mae began allowing servicers to proactively contact borrowers who may be close to or eligible for mortgage-insurance termination based on current property value. The underlying eligibility requirements did not automatically disappear or become easier.
What LTV do I need to remove PMI based on current value?▾
For a one-unit primary residence or second home, Fannie Mae generally requires 75% LTV or less when the mortgage is between two and five years old, or 80% or less after five years. Other property types and improvement scenarios have different requirements.
Can I remove PMI before two years?▾
Normally Fannie Mae has a two-year seasoning requirement for current-value cancellation, but it may be waived when qualifying improvements made by the borrower increased the property value. The current-value LTV generally must then be 80% or less.
Will Fannie Mae automatically remove PMI because my home increased in value?▾
No. The new rule permits proactive servicer outreach. Current-value cancellation still requires the applicable evaluation and property valuation.
Do I need to refinance to eliminate conventional PMI?▾
Not necessarily. Depending on the loan, PMI may terminate through federal automatic-cancellation rules or an eligible borrower/current-value termination request without replacing the first mortgage.
Does the same rule apply to FHA MIP?▾
No. FHA mortgage insurance follows separate HUD requirements. For many FHA loans assigned case numbers on or after June 3, 2013, the original LTV determines whether annual MIP lasts 11 years or for the mortgage term.
How can I see whether Fannie Mae owns my loan?▾
Fannie Mae provides an official Loan Lookup Tool, and your mortgage servicer can also confirm the investor associated with your mortgage.
Authoritative Sources
- Fannie Mae — LL-2026-07: Updates to Mortgage Insurance Termination Requirements
- Fannie Mae — Conventional Mortgage Insurance Termination Guide B-8.1-04
- Fannie Mae — Property Valuation Procedures and Current Fees for MI Termination
- CFPB — When Can I Remove PMI From My Mortgage?
- Fannie Mae — Consumer Loan Lookup Tool
- HUD — FHA Mortgage Insurance Duration Guidance
- Freddie Mac — Mortgage Rate Survey Archive, Sept. 24, 2026
This is not a commitment to lend. All loans are subject to credit approval, property approval, program guidelines, and applicable terms. Programs, rates, terms, and conditions are subject to change without notice. Not all applicants will qualify. Equal Housing Opportunity.
Angel Taipale, NMLS #1736690 — Bright Horizon Lending Inc., NMLS #2565670. Verify on NMLS Consumer Access